Latest issue
Closing a Paid-Off Card Feels Satisfying. It's Usually a Mistake.
9/11/2026
You pay off a credit card. The balance hits zero. Your first instinct is to close the account — get it off your plate, simplify your financial life, maybe cut up the physical card for the tactile satisfaction of it. This impulse is completely understandable and almost always wron…
Recent posts
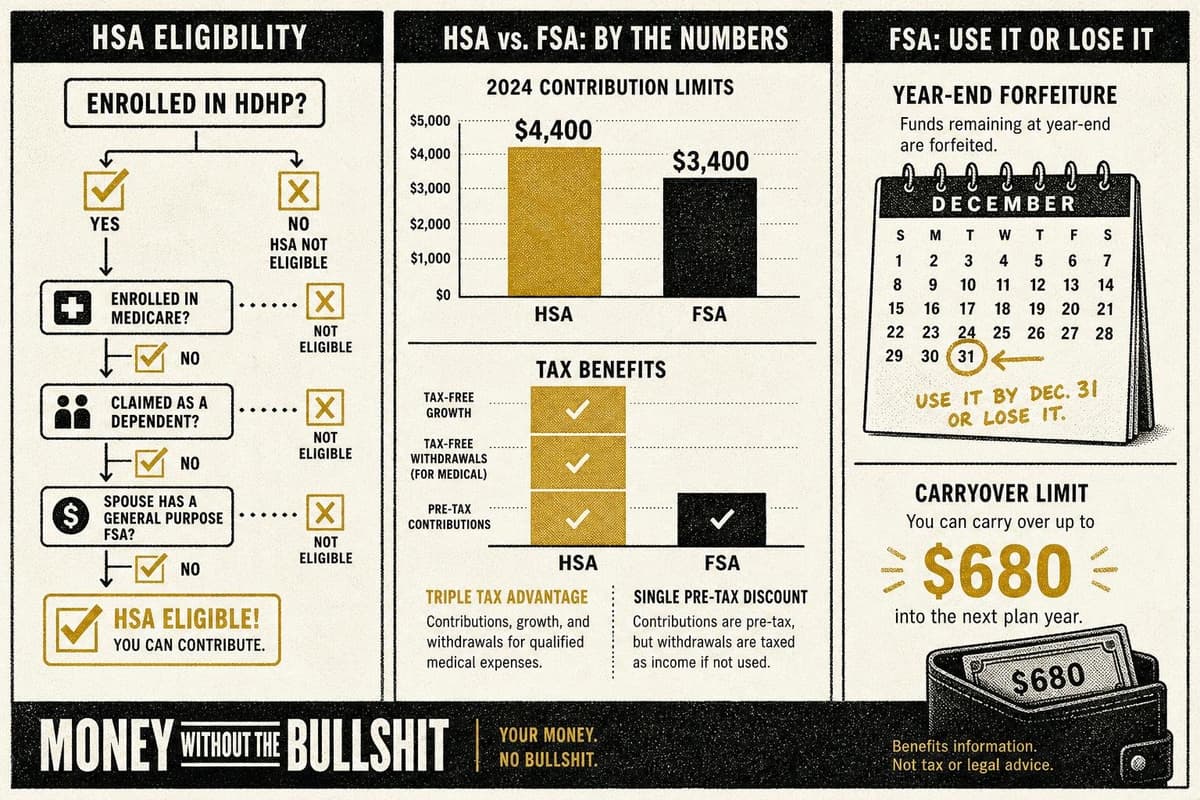
Most people treat this as a comparison between two similar accounts. It isn't. An HSA and an FSA are solving different problems for different people, and the "which one saves more…
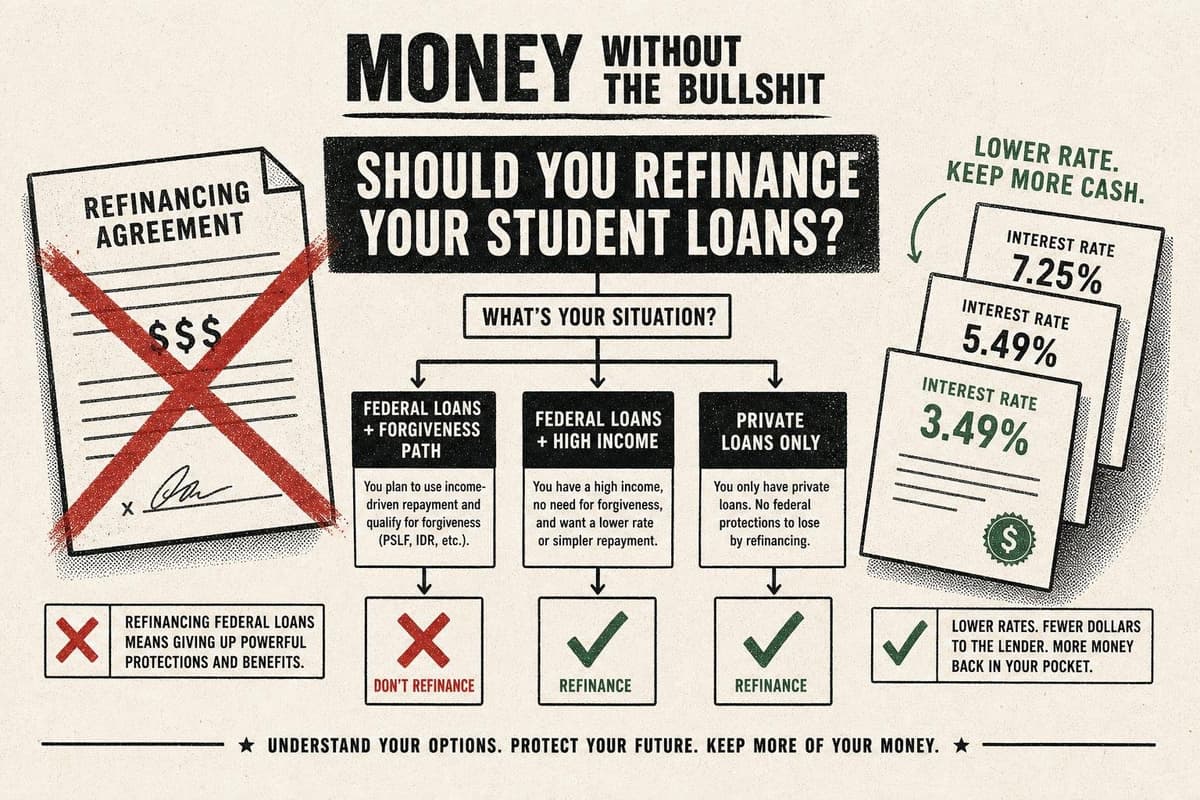
The standard pitch for refinancing student loans goes like this: you're paying a high rate, private lenders will give you a lower one, you save money. Simple arbitrage. Run the num…
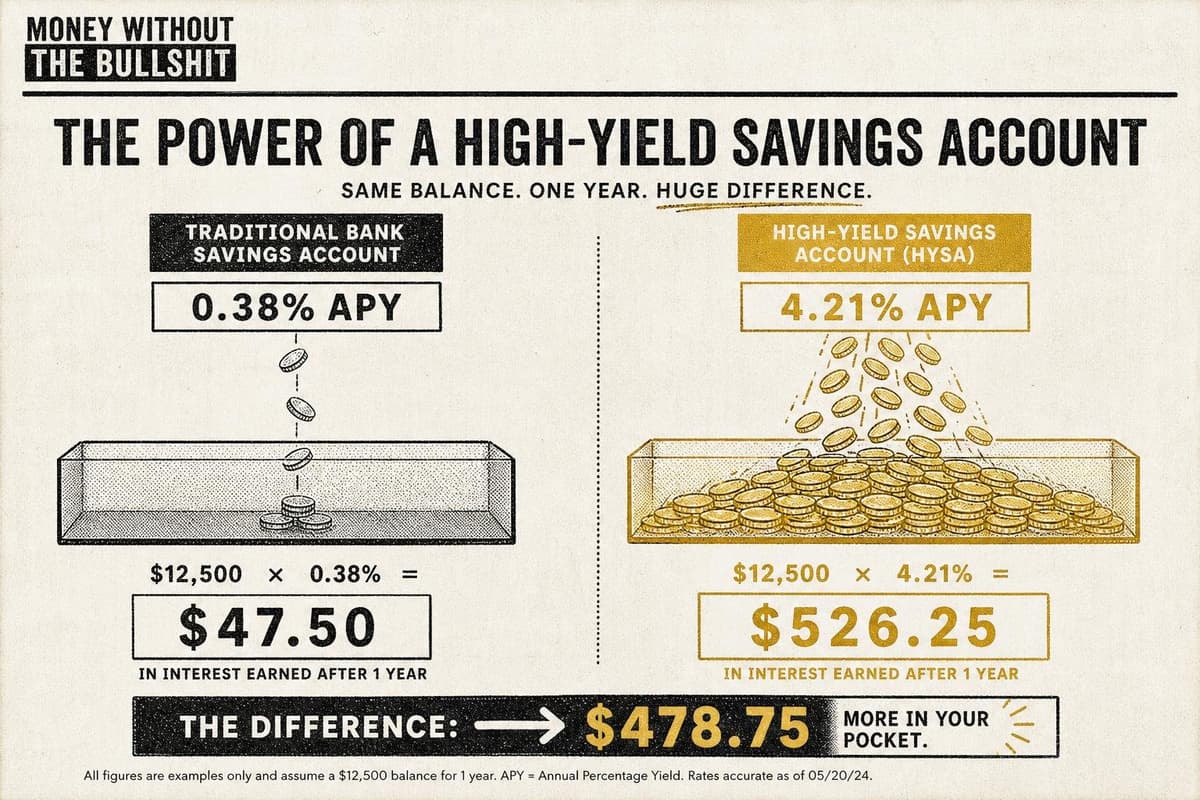
Most people treat their emergency fund as a parking problem — get the money somewhere safe, stop thinking about it. The "somewhere safe" they pick is usually the same bank that han…
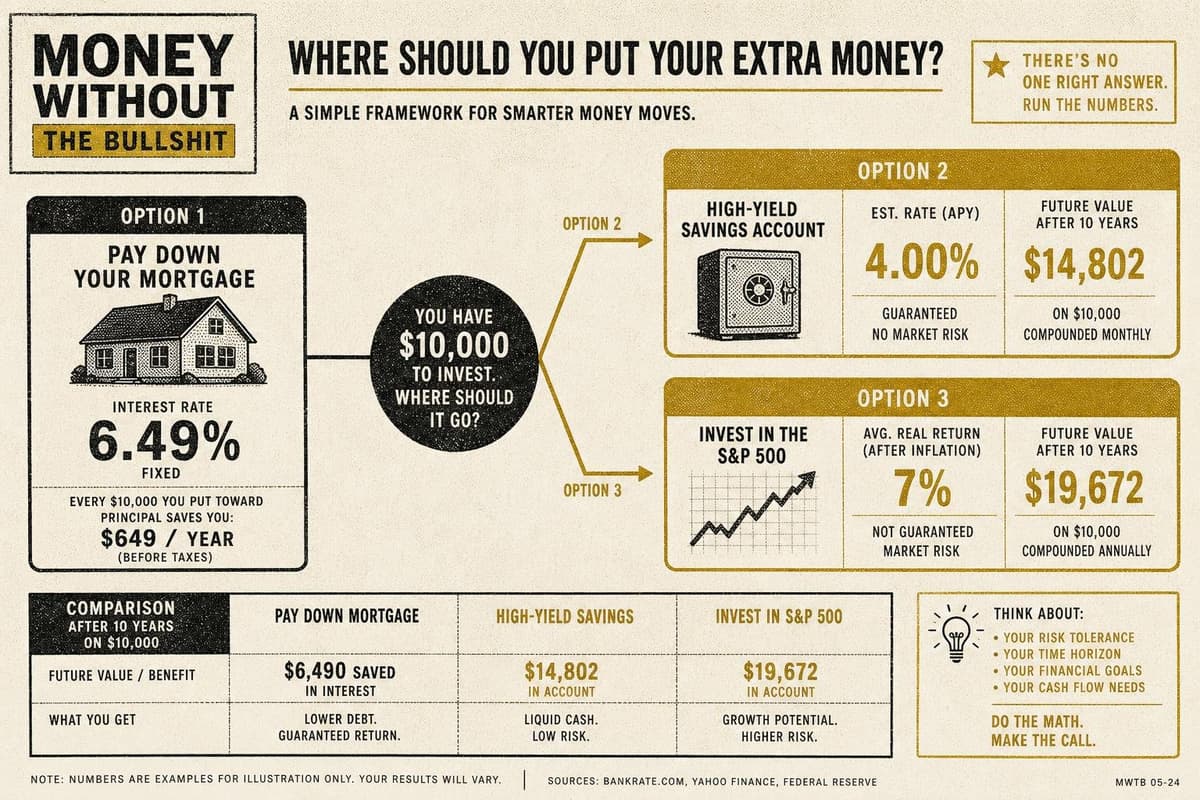
For a decade, the answer to "should I pay off my mortgage early?" was basically: no, obviously not, go invest. When 30-year mortgages were sitting at 3%, paying one down early to "…
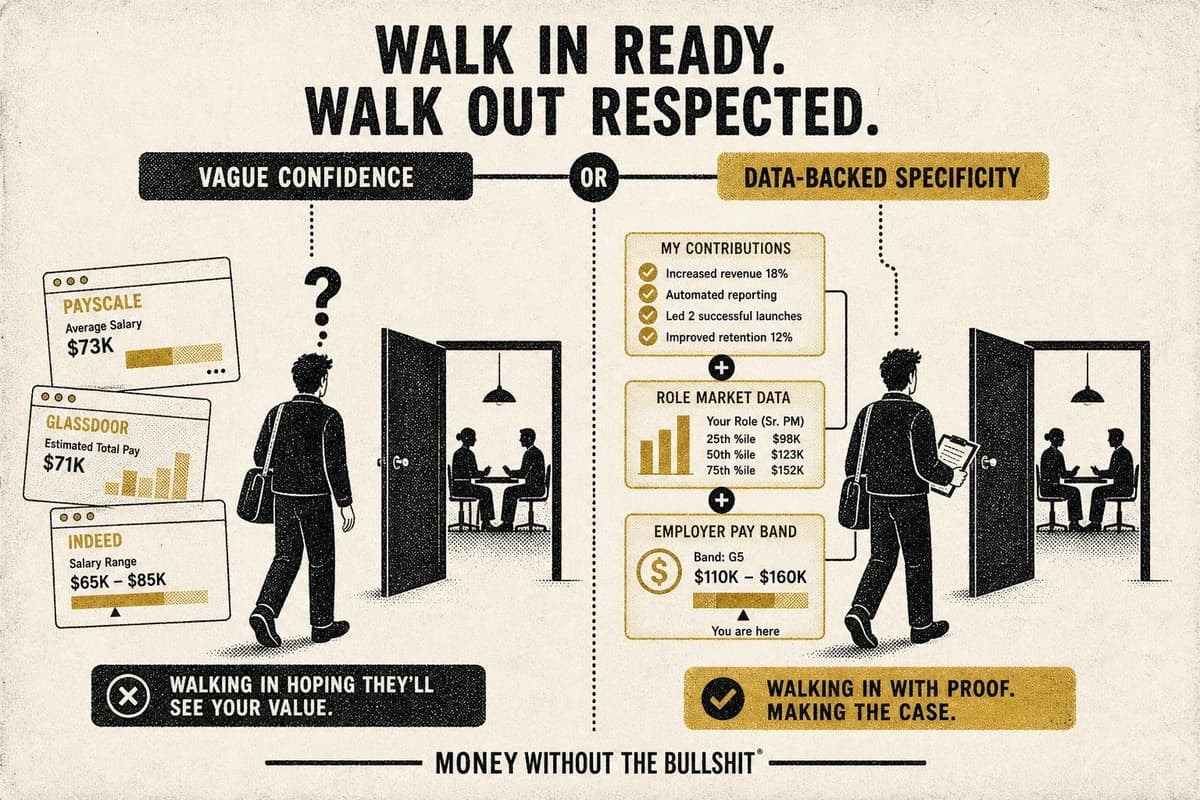
Most people treat salary negotiation like a performance — they rehearse what to say, steel their nerves, and walk in hoping to seem confident enough. Then they accept whatever numb…
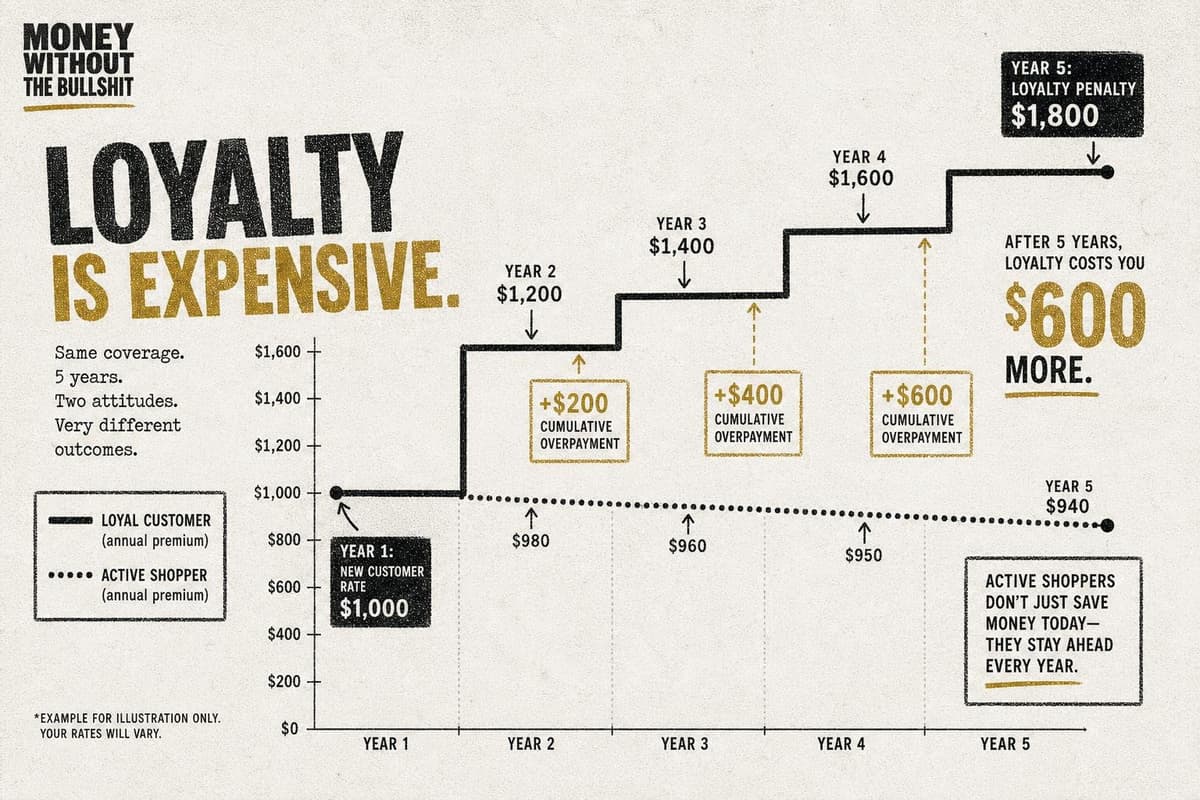
The auto insurance industry has a business model that depends on inertia. You sign up, set up autopay, and forget about it — and every year your premium quietly climbs while your i…
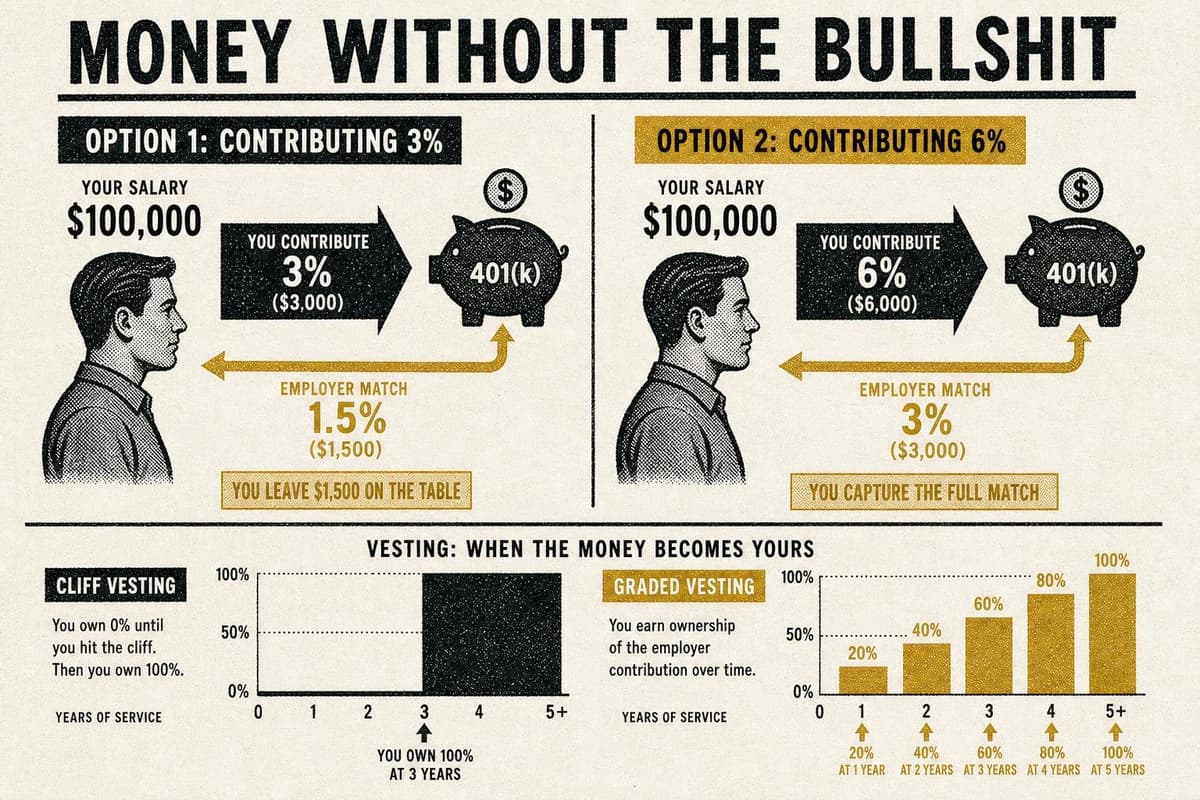
You get a new job. HR walks you through benefits. Someone says "we match 50% of your contributions up to 6% of your salary" and your brain files it under "good, I should do that" —…
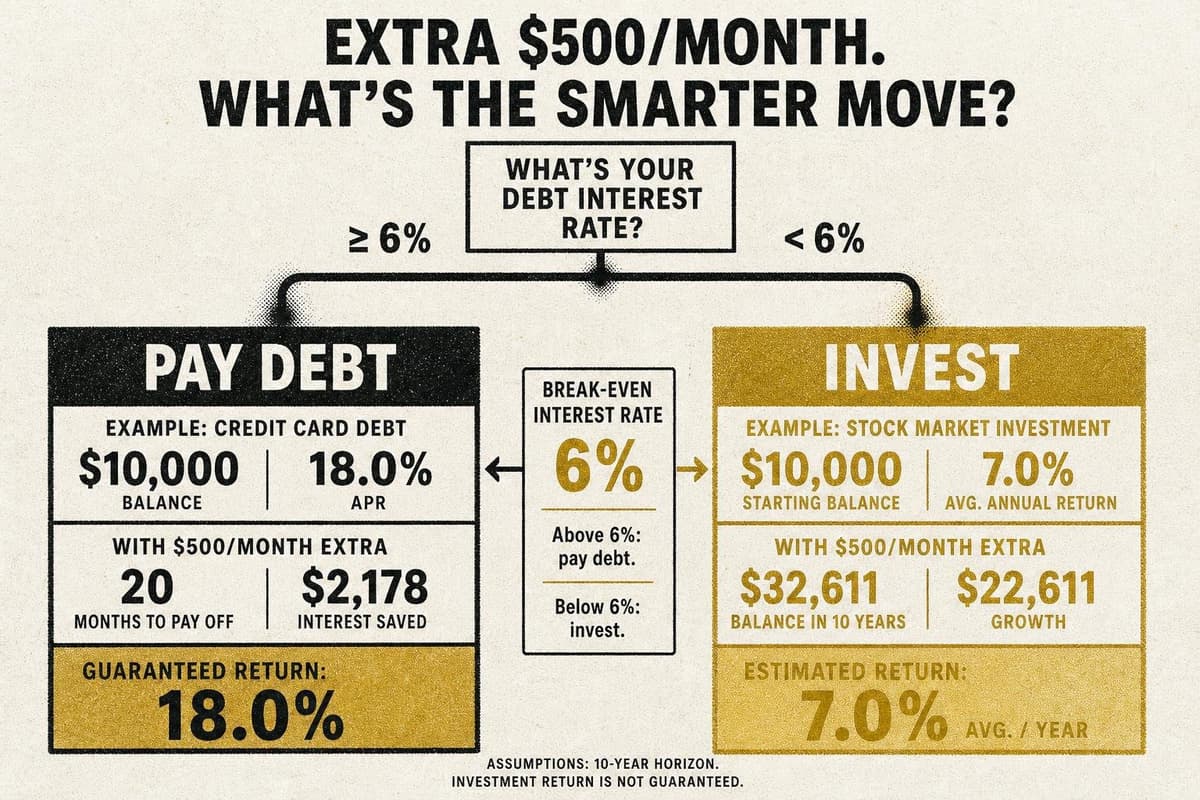
You have $500 extra this month. Your student loan is sitting there. So is your 401(k) enrollment form. The conventional wisdom says: kill the debt first, sleep better, then invest.…
Most people with an HSA treat it like a medical checking account: money goes in, money comes out when something hurts. That's not wrong, exactly — it's just leaving the most tax-ef…
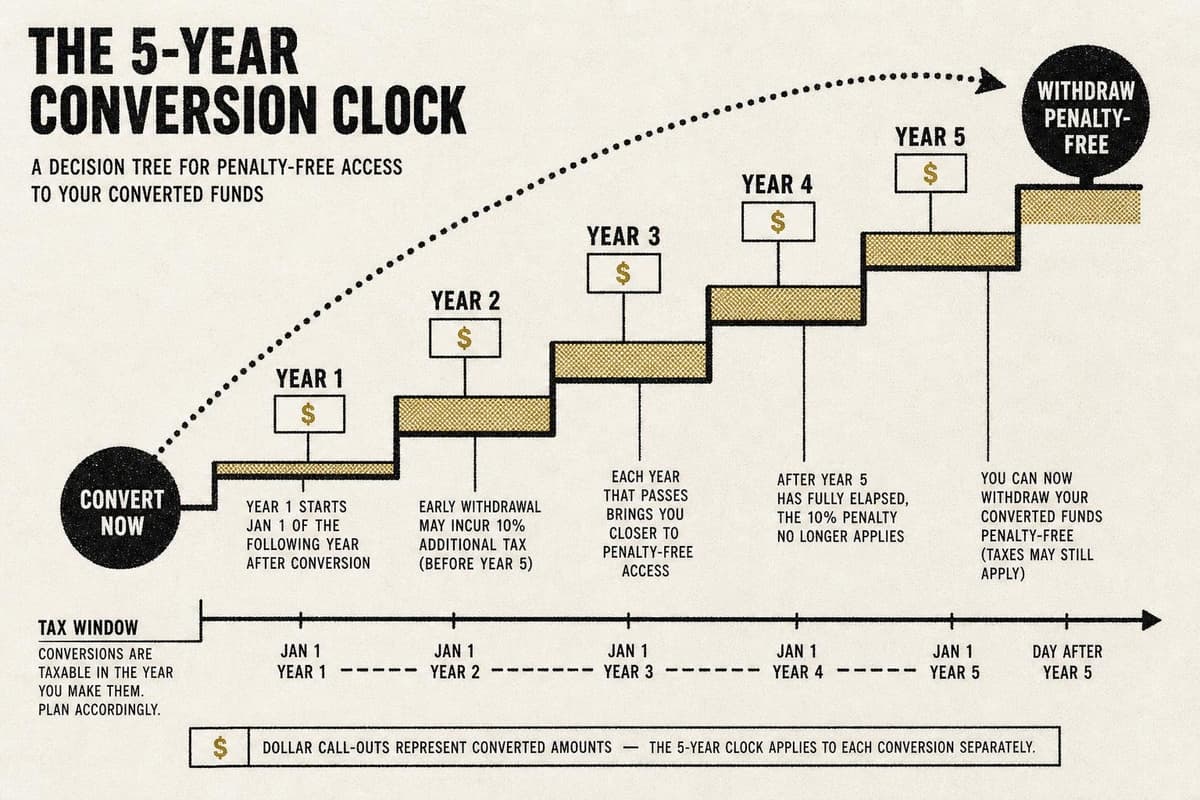
Most people who hear "Roth conversion ladder" file it under "complicated tax stuff for people with too much money and time." That's a mistake. The core idea is simple: you have mon…
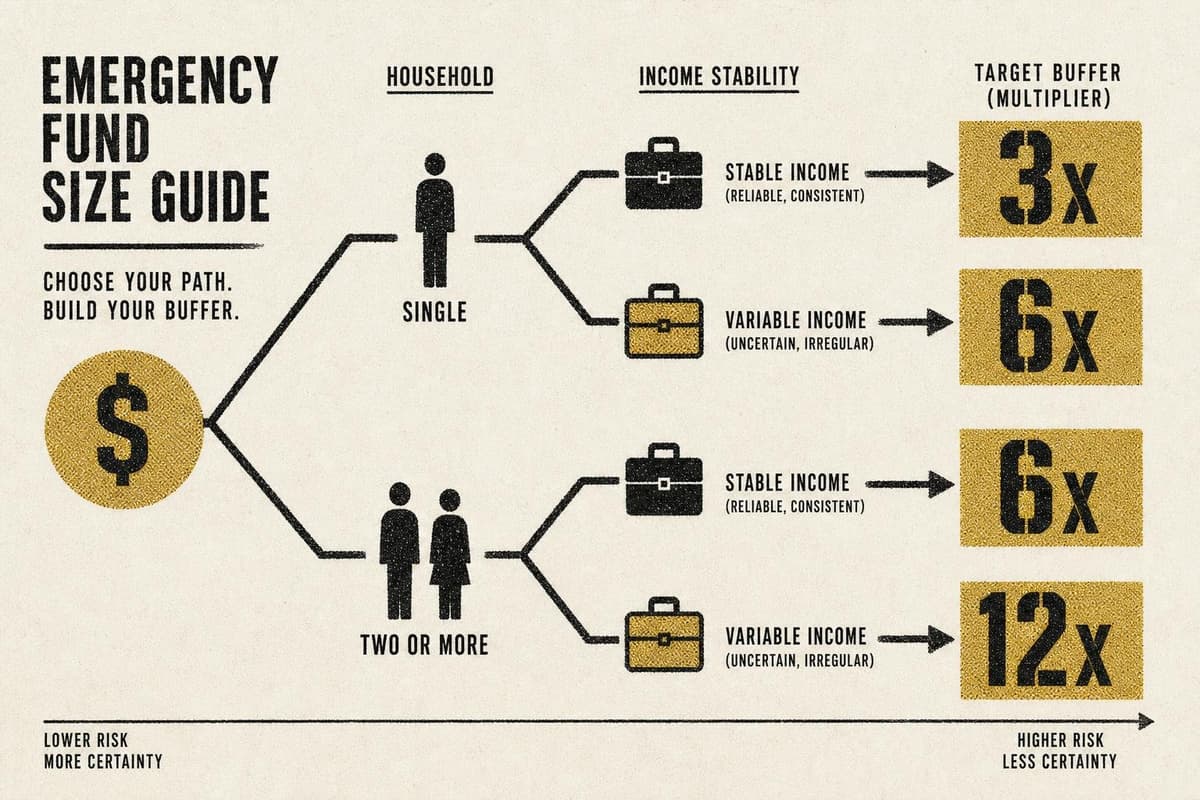
The standard emergency fund advice has survived for decades because it's directionally correct: having a cash buffer is better than not having one. But "3-6 months of expenses" is…
There's a version of personal finance advice that treats all debt like a house fire. Get out fast, stop drop and roll, don't look back. And for high-interest revolving credit card…
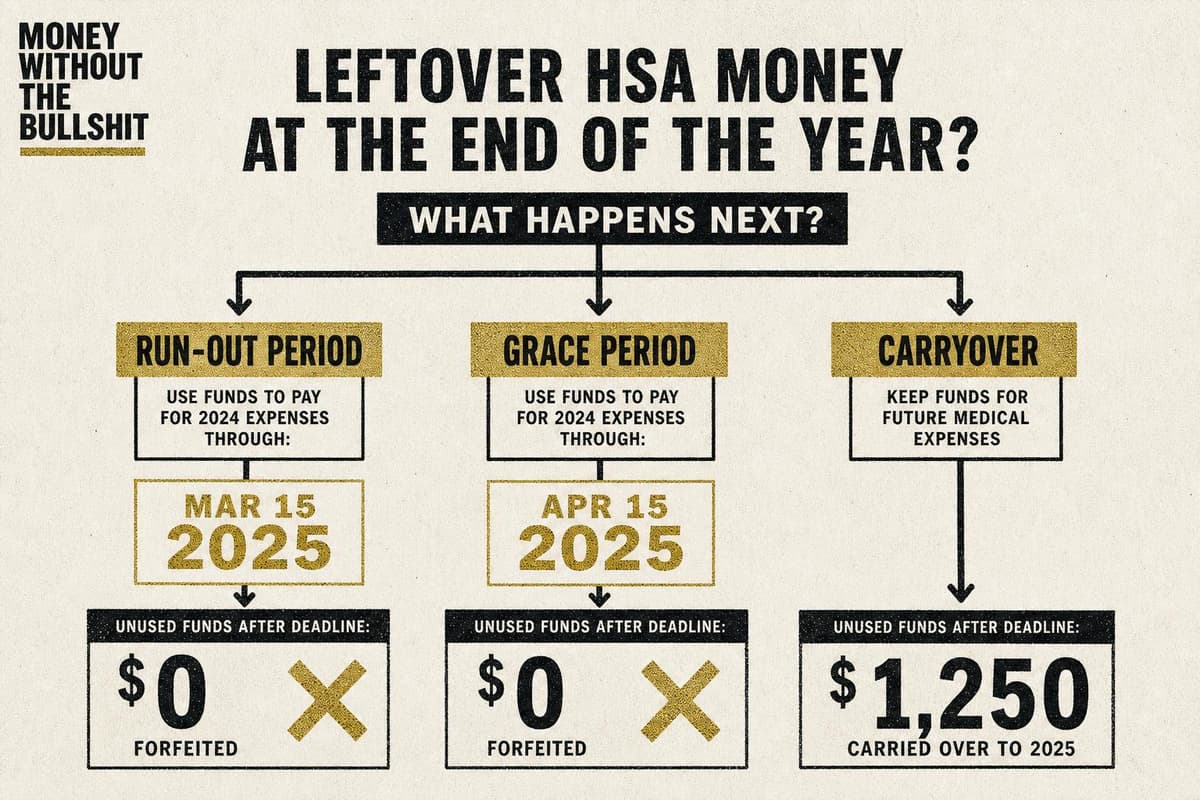
You set aside pre-tax money. You forgot about it. Now December is approaching and you're panic-buying a thermometer you don't need. This is not a spending problem. It's a systems p…
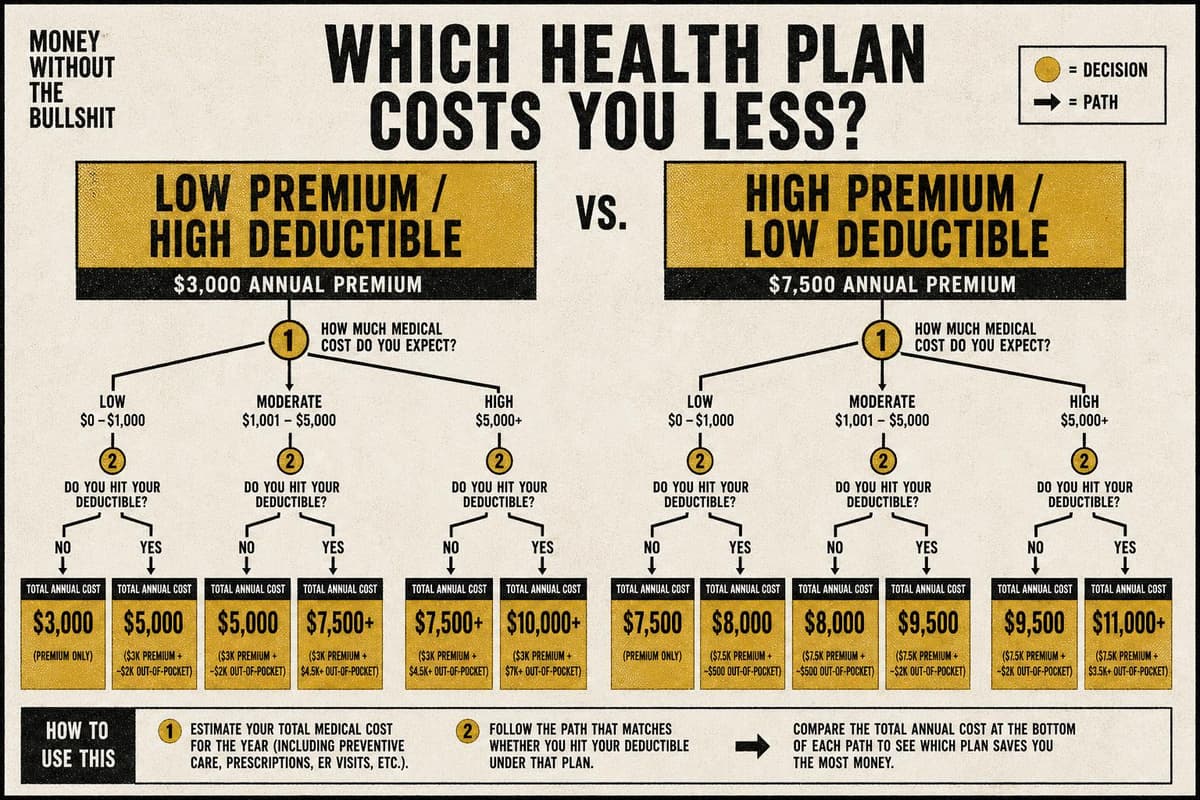
Most people pick their health insurance by looking at one number: the monthly premium. The lower it is, the better the deal. This is exactly backwards. The premium is what you pay…
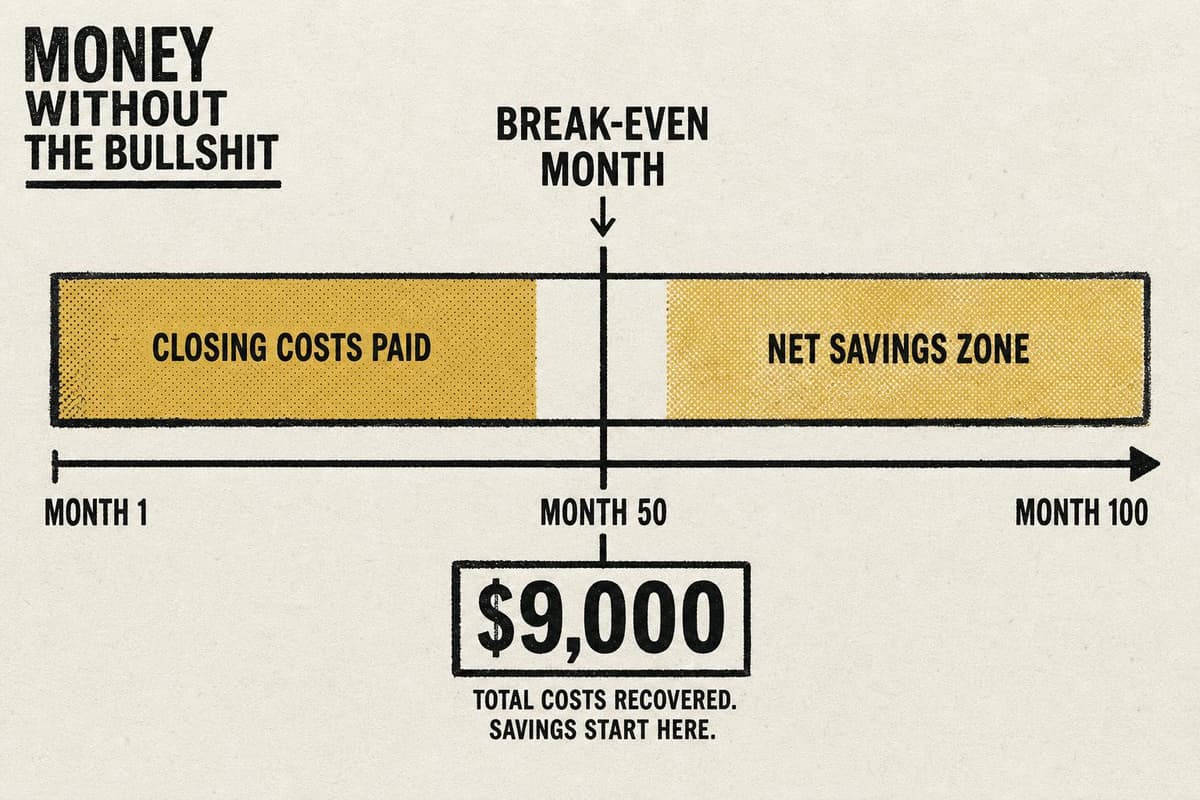
The most common piece of refinancing advice is that you should refinance when rates drop at least 1% below your current rate. It's tidy, memorable, and wrong — or at least, wildly…
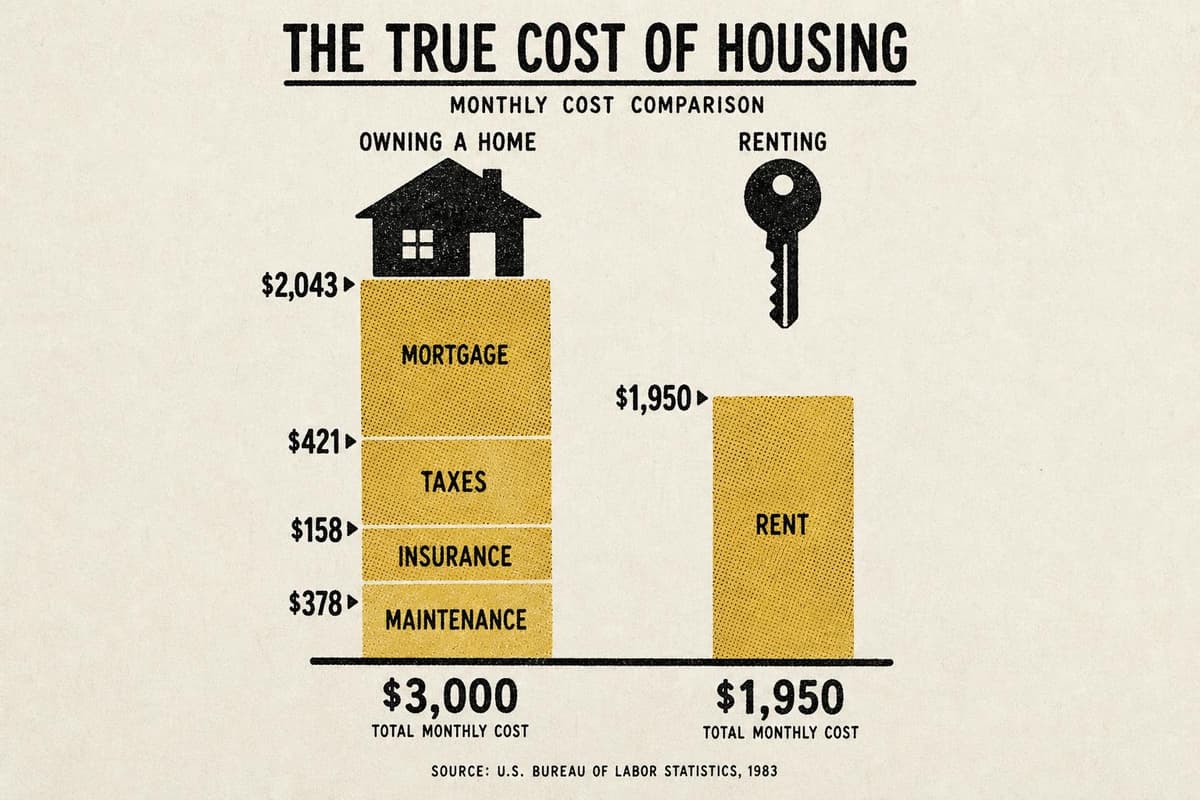
The standard rent-vs-buy calculator asks for your home price, your mortgage rate, and how long you plan to stay. It spits out a monthly number. You compare it to your rent. You mak…
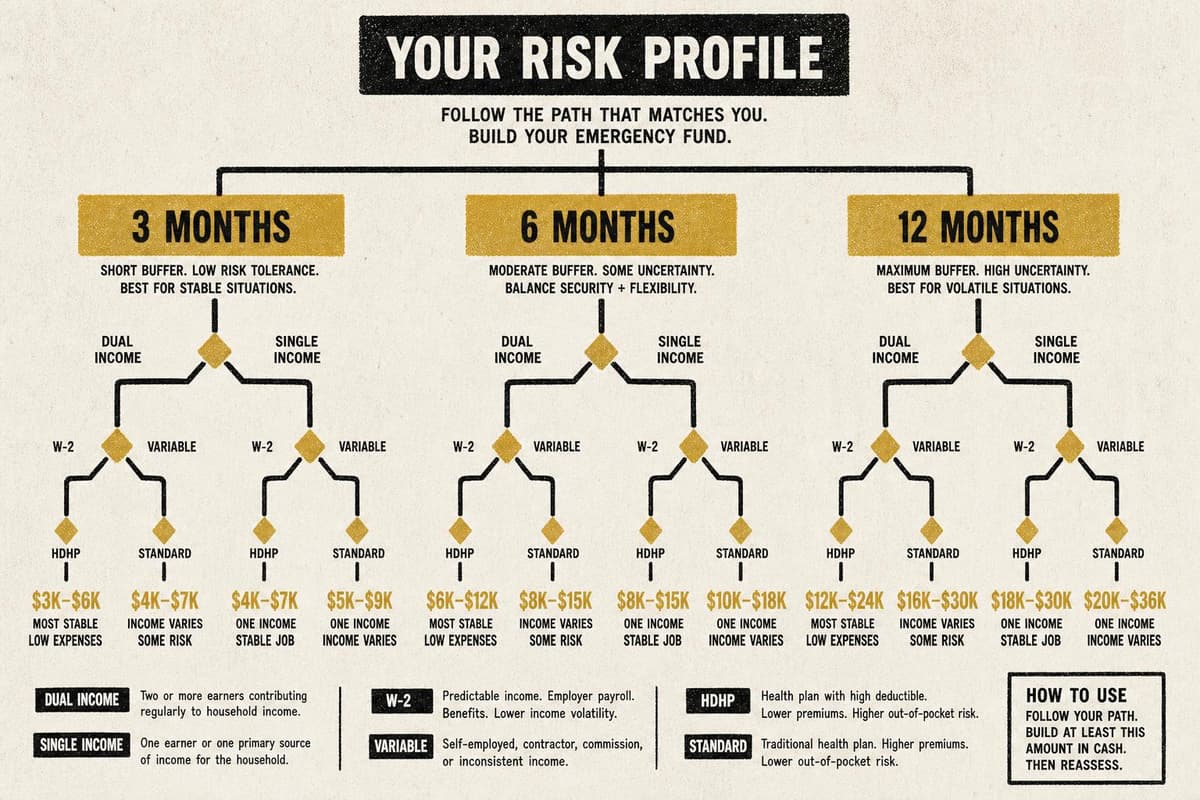
The standard advice sounds so clean: save six months of expenses, done. But "six months" is a number that was designed for a person who doesn't exist — stable W-2 income, two earne…
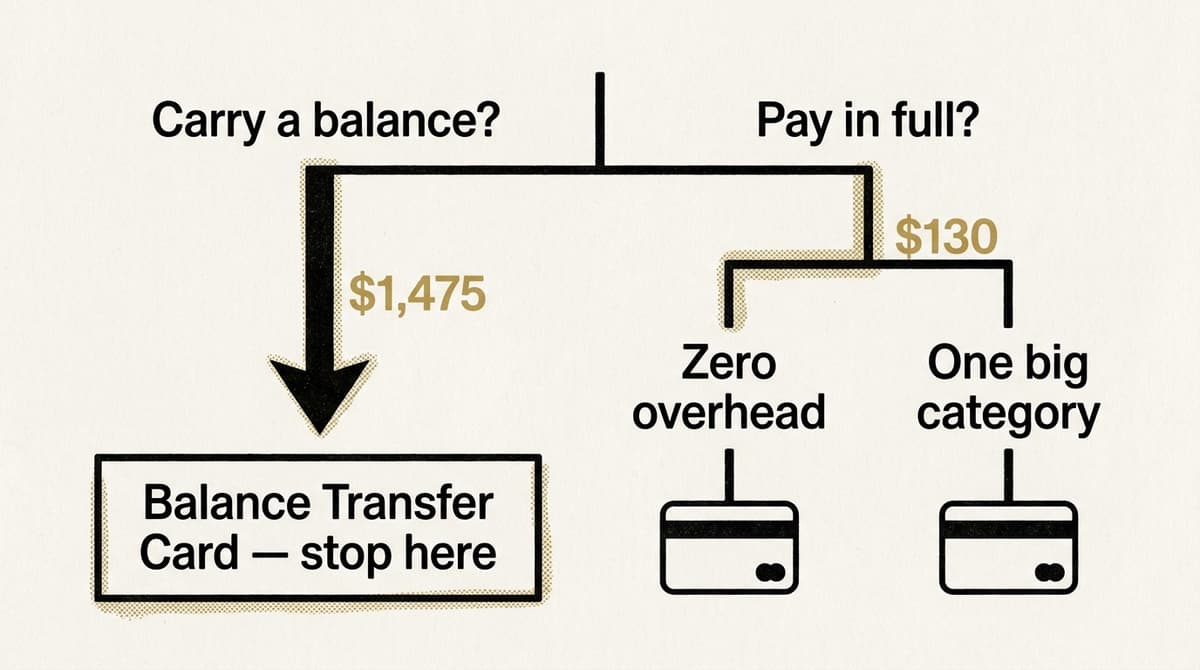
Here's the math that most rewards content skips: if you carry a $6,500 balance at a 23% APR, you're paying roughly $1,475 a year in interest. A 2% cash back card on average spendin…
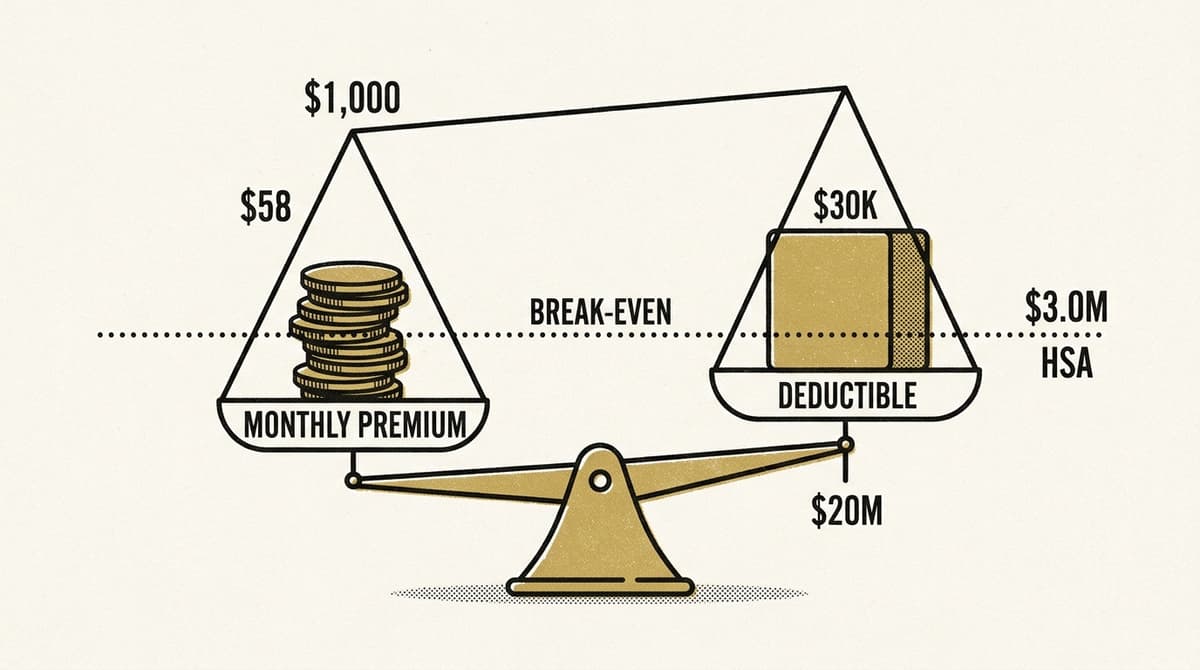
Most people pick their health insurance deductible the same way they pick a seat on an airplane — grab something that looks reasonable and stop thinking about it. The result is usu…