


Harvest is hitting the Lower Mississippi right when the river doesn't have the water to carry it efficiently. The numbers from the week ended October 17 tell a story that's more interesting than "congestion" — it's a capacity squeeze measured in inches of draft, not container counts.
The Volume Is There. The Draft Isn't.
Barges unloaded 873 loads of grain in the New Orleans region that week, 16% more than the prior week, with barged grain movements of 522,313 tons — up 31% week-over-week but still 7% below the same week in 2025, according to USDA's Grain Transportation Report as reported by Louisiana Trade & Commerce. Some 344 barges moved downriver through the key locks, 91 more than the week before. This is internal river logistics — barges feeding the export pipeline, not the export pipeline itself — and it's running hot even while lagging last year's pace.
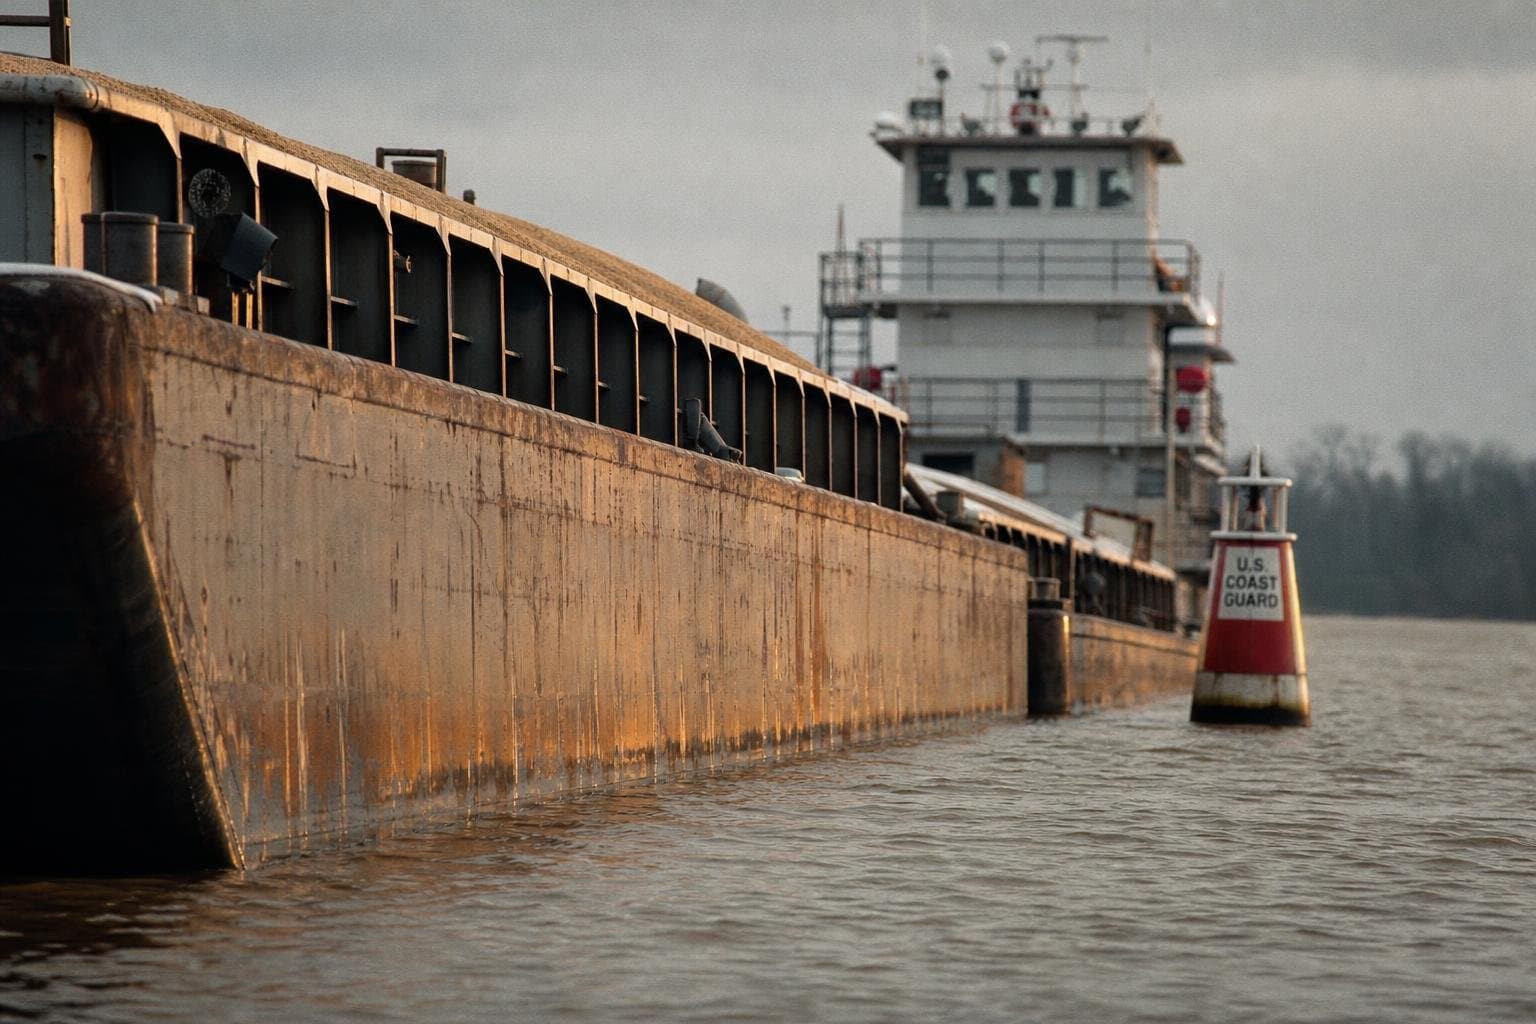
The reason it's lagging isn't demand. It's the Coast Guard's low-water restrictions, which cap southbound barge drafts at 11 feet 6 inches between mile 869 (north of Memphis) and mile 585, and 12 feet 6 inches from there down to mile 303 above Baton Rouge, with tows limited to seven barges wide. Northbound traffic is held to 10 feet 6 inches (Louisiana Trade & Commerce). A shallower draft means less grain per barge, so the same harvest requires more trips, more tow movements, more lockages — more of everything except the one resource that's scarce: water under the hull.
And the restrictions are about to get tighter, not looser. Inland Rivers, Ports & Terminals is circulating a draft/tow-size proposal for the Lower Mississippi and Ohio Valley sectors effective October 26, driven by what the group describes as falling river stages, which would further cap barge configurations at no more than six wide by seven long overall (IRPT). That's a planning notice, not yet an enforced order, but it signals operators are bracing for another downward step in tow capacity just as harvest volumes are supposed to be peaking. It's a reminder of how congestion risk in bulk-cargo networks often shows up first as a formal restriction notice rather than a visible backlog — the same pattern port-side monitoring tools try to flag before queues actually form at anchorages elsewhere in the world (Portcast).
The Export End Hasn't Choked — Yet
Here's the part that matters for anyone pricing export risk: the deep-draft channel below Baton Rouge is still fine. The New Orleans Board of Trade's daily port update put the controlling draft for oceangoing vessels at 50 feet as of October 22, with dredges actively working Southwest Pass and the crossings above the city (Louisiana Trade & Commerce). Thirty-one oceangoing grain vessels loaded in the Gulf in the week ended October 15, 3% more than a year earlier — outbound flow is still clearing. But the forward look softened: only 45 vessels were expected to load over the following 10 days, four fewer than the same period last year. Grain inspections at Gulf ports did rise 15% week-over-week to 1.51 million metric tons, so nothing in the export numbers screams distress. The strain is upstream, in the internal barge network, not yet at the vessel-loading interface.
Rates Are Already Pricing the Draft Problem — and the Forward Curve Disagrees
St. Louis barge rates were running 20% above year-ago levels as of the latest reporting, a premium that shows up on top of byproduct and feed markets that were already running hotter than a year earlier back in the spring, per USDA's National Grain and Oilseed Processor Feedstuff Report (USDA AMS). The systemwide freight premium shows up clearly in USDA's AgTransport tariff data for week 42: Twin Cities at 800, Mid-Mississippi at 786, Lower Illinois at 773, Cincinnati and Lower Ohio both at 725, against a lighter 493.5 at Cairo-Memphis (IndexBox). What's worth watching is the forward curve embedded in that same dataset — one month out, every one of those same locations is priced lower: Twin Cities down to 754, Mid-Mississippi to 728, Lower Illinois to 672, Cincinnati/Lower Ohio to 641. The market is betting the draft restrictions ease as harvest flow normalizes and river stages recover seasonally, not that the current premium holds through the quarter.
That bet is the thing to track. If the October 26 tow-size tightening takes effect as proposed and persists into November, the forward curve's assumption of relief gets tested directly — and a rate curve pricing in a decline while physical tow capacity is shrinking is exactly the kind of mismatch that resolves badly for whoever's holding barge freight contracts on the wrong side of it. Watch the next AgTransport tariff release against whatever IRPT reports once the new configuration limits are actually enforced.